Subscribe to Being Broke Sucks Latest Updates

Personalized Credit Consulting

Tuesday, October 6, 2009

Why Renting Is Better Than Buying

 Renting Vs. Buying

You’ve probably heard statements like these plenty of times. On television, radio, the internet, and in casual conversation. Such sentiments are common in any discussion that involves home-buying and personal finances. It’s common knowledge that buying a home is a better financial move than renting. After all, you’re building equity instead of throwing away your money, right? Well, maybe not quite… Rather than assuming the “common knowledge” on this subject is accurate, let’s take a look for ourselves at some of the financial differences between renting and home-buying.


MyCreditGroup.com


A Real-World Example

For the purpose of comparing renting to owning in this article, I’ll be using real-world data gathered from my area (San Francisco Bay Area). Although most first-time buyers tend to move from renting an apartment to buying a larger, stand-alone house, as much as I can I will compare apples to apples.
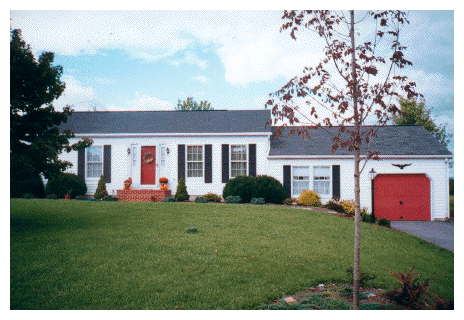
  • For rent, I located a 3-bed, 2.5-bath, 1,840 sqft house with an attached 2-car garage, on 0.2 acres. Monthly price: $1,495.
  • For purchase I found a 3-bed, 2.5-bath, 1,850 sqft house with an attached 2-car garage, on 0.22 acres. Price: $424,950.
The two homes are located within two miles of each other in similar neighborhoods, and neither is located on a busy road. We’ll assume that our hypothetical homebuyer is a married couple with $85,000 in the bank to make a 10% down payment. To calculate mortgage payments we will use a recent 30-year fixed interest rate of 5.35%.
Let’s look at how the monthly costs break down (approximately) for our hypothetical potential first-time homebuyer:

Renting  
Buying  
Rent/Mortgage:  
$1,495
$2,135
Insurance:

$163
Property Tax:
-
$407
Tax Savings*:
-
($327)
Maintenance:
-
$354
Total:
$1,495
$2,732
*: (less standard deduction)
Right off the bat, you see that simply trading straight across from renting to owning results in a 82% more expensive monthly bill. That’s not exactly chump change. With even a slight upgrade from renting to buying (which most first-time buyers are prone to do), you can easily see how the total monthly costs would be more than double.

“If you rent, you’re throwing away your money.”

Common knowledge says that despite today’s large premium, buying a home is a “good investment”. Hey, at least you’re not “throwing away” your money, right? True, the renter in my scenario spends $1,495 every month that they will never see again. I wouldn’t exactly say it has been “thrown away” any more than money spent on any other good or service is “thrown away,” but granted, there is zero financial return on that money.
However, when you take a look at the breakdown of the homebuyer’s monthly expenses, a large amount is money that will never return, either. Insurance, property tax (less tax savings), and maintenance, add up to $570 every month that is being “thrown away.” Even worse is the amount spent on mortgage interest. Consider how much of a mortgage payment is applied toward loan interest throughout the life of a 30-year fixed loan:
Years  
% toward interest
0-5
~80%
6-10
~70%
11-15
~60%
16-20
~50%
21-25
~35%
26-30
~10%
In the first five years, approximately 80% of the mortgage payment goes toward interest. That’s an additional $1,705, for a total of $2,275 being “thrown away” every single month by the homebuyer for the first five years. Ouch! In fact, not until the homebuyer has been paying down the mortgage for over 20 years will the amount they are “throwing away” be less than the renter.


Books at Buy.com!


“Owning your own home is a forced savings plan.”

As you can see above, if home buying is like a savings plan, it’s probably the worst savings plan on Earth. Would you voluntarily sign up for a savings plan where well over half of the money you deposit in the first 20 years simply vanishes, and from which you can only withdraw money by relocating and paying a 6-9% fee (not on the amount you have “saved” mind you, but on the total sale price of the home)? Of course not. That doesn’t sound anything like a savings plan.

If our potential homebuyer has that $42,500 saved up for a down payment and deposits it along with just half of the monthly savings over buying ($618 per month) into an account at 8% interest, the balance will be nearly $300,000 in just 10 years. That’s a liquid investment, that can be used for whatever you want, no relocation required. Buying a home is not a savings plan. Actually saving money every month is a savings plan.


“Home ownership is an excellent path to build wealth.”

If your goal is to build wealth, you will be much better off investing your money in the stock market than buying a home. While both stocks and housing are cyclical markets, long-term historic trends show that housing appreciates at a rate barely above inflation, while stocks tend to return an inflation-adjusted 7-10%.In my hypothetical scenario a renter who invested in the stock market with the $42,500 down payment plus the monthly difference between the $1,495 rent and the $2,732 home-buying costs would be over $500,000 better off after 30 years than the homebuyer, assuming 4% average appreciation.

An important thing to consider is that home prices in the United States are just now beginning to correct from an enormous unprecedented run-up in recent years. Despite what those in the business of selling real estate may insist, the correction in housing is still in the early stages. Four percent is most likely overly optimistic for most areas in the next 5-10 years. The only thing we know for sure is that double-digit gains are gone and won’t be coming back any time soon.

Also keep in mind — I mentioned it above but it bears repeating — in order to cash in on any “wealth” you build through your home you will need to sell that home and move. No, “extracting equity” does not count, since that simply results in a larger debt. Debt is not equal to Wealth.

Conclusion
For most people buying a home will result in their largest monthly bill (by far), and because they believe that it will bring them wealth or that they are “throwing away their money” if they rent, they often take on a much larger home debt than a prudent budget would allow. It is a real shame when people are driven to get into the housing market because of misplaced notions of imagined financial benefits. Of course, everyone’s circumstances are different, and for some (particularly those that live away from the coasts) the numbers may actually work out in favor of buying.

Don’t misunderstand me here. I am not saying that no one should buy a home, or that my example scenario is a golden standard of truth for all. Don’t take my word for it. Run the numbers for yourself, check out other articles (a small collection is listed below), and do what works for you. I highly recommend the great graphical calculator from The New York Times for comparing the financial aspects of renting and buying. Many people will consider all of the consequences — financial, emotional, etc. — and conclude that buying a home is the best decision. Just don’t trick yourself into thinking it’s a good financial decision if it’s not.
I myself intend to buy a house some day. However when that day comes, I will be buying a house because I want a nice, “permanent” place to live where I’m the boss, not because I think it will help me get me rich.

Additional Resources

Wall Street Journal: Your Home Isn’t the Nest Egg That You May Think It Is
New York Times: A Word of Advice During a Housing Slump: Rent
New York Times: Is it better to buy or rent? (graphical calculator)
The Motley Fool: The Worst Investment Ever
SmartMoney.com: Renting Makes More Financial Sense Than Homeownership
CNN Money: Stocks vs. Real Estate
Priced Out Forever: Renting vs. Purchasing

 Mr.Dangerfield is an I.A.P.D.A Certified Debt Specialist whom has worked in the finance industry for over a decade. He manages www.beingbrokesuckstoday.com and is the author of "A Dangerfield Manifesto" and co-founder of SMG Holdings, the parent company of Squad Music Group, Dangerfield Artistic Entertainment SMG Publishing and Taboo Dangerfield Publishing
Follow me on twitter

Friday, October 2, 2009

Survival Guide for the uninsured and Broke!!

 The Uninsured Survival Guide


The more than 46 million Americans without coverage will get sick more, earn less and die earlier than those with insurance. Here's where to find help if you're caught without it.

If you recently lost your health insurance, or if you've never had coverage, then you're part of an unfortunate but growing national trend.

The ranks of the uninsured have grown by nearly 18% just since 2000, according to a study updated in 2006 by the Kaiser Commission on Medicaid and the Uninsured. More than 46 million people under 65 lack insurance, and millions more are considered underinsured, with gaps in their coverage that leave them exposed to catastrophic medical bills.


In fact, medical bills are a factor in about half of all consumer bankruptcies filed, according to a Harvard University study.


The uninsured die sooner

But financial troubles aren't the only risk. According to an earlier Kaiser report:

  • People without health insurance receive less preventive care and are less likely to have major diseases detected early.
  • The uninsured are more likely to die prematurely than the insured, with various studies putting the mortality rate for the uninsured somewhere between 1.2 times to 1.6 times the rate for the insured.
  • Uninsured infants have relative odds of dying that are 1.5 times higher than infants with private insurance.
  • The poorer health associated with being uninsured depresses workers' average lifetime earnings significantly. The commission estimated that better health would boost earnings by 10% to 30%. 
  •  
If you don't have insurance, there are things you can do to protect your health and pocketbook. Before we get into those, however, I want to tell you about some ways you might be able to find insurance coverage that you might not have considered.

Some of the options include:

COBRA: If you were covered by health insurance at work but are about to lose your job, you're typically entitled to coverage for up to 18 months under the federal Consolidated Omnibus Budget Reconciliation Act of 1985. Unfortunately, you have to pick up the whole tab for this coverage, which can be tough to afford. Coverage for a family of three can easily cost $500 to $1,000 a month.

High-deductible policies: You'll pay more of your routine medical costs out of pocket, but these policies protect you against catastrophic medical bills. Having the coverage also entitles you to insurer-negotiated discounts with doctors and hospitals. (It's shocking, but many medical providers charge the uninsured higher rates and fees because they aren't covered by such discounts.)

An individual HMO policy from Blue Cross with no deductible might cost a single 24-year-old female in San Francisco $330 a month. Choose a plan with 20% co-pays and a $1,000 deductible, however, and the cost drops to $62 a month.

Short-term coverage: Many insurers that provide individual policies have a bridge or short-term option, designed to cover you until you land your next job. These are typically cheaper than a regular individual policy because the insurer is exposed to claims for a limited time. Try the nearest Blue Cross, or talk to an experienced health-insurance broker.

High-risk pools: If a health issue, rather than the cost, is keeping you from being insured, check to see if your state has a high-risk insurance pool. Georgetown University's Health Policy Institute maintains a list of state high-risk programs and contact information.

Health insurance for kids: Most states sponsor low-cost or free health insurance for children, and a few will cover their parents for an additional fee. A family of four in most places can qualify for insurance for their kids with an annual income up to $34,100; in higher-cost areas, that limit may be higher. For more information, visit Insure Kids Now!, a government-run Web site.

Medicaid: This government-funded coverage is generally reserved for people with very low incomes and few assets; each state has different guidelines. For more information, visit Centers for Medicare and Medicaid Services.

If none of those options works for you, you'll be relegated to a patchwork system of government and charitable programs that try to provide help for America's uninsured.

Because there are more than 46 million such people, however, that means some of these resources are overwhelmed.

That doesn't mean you should delay screenings and treatments, only that you may need to wait longer for an appointment than if you were privately insured.
Low- and no-cost health care
Here are some of the resources available for various kinds of treatment:


Routine and diagnostic care: Hundreds of community health centers around the country offer free or low-cost care. To find a site near you, visit the Bureau of Primary Health Care.

The national Centers for Disease Control and Prevention has information on state health departments, which provide additional clinics and resources for the uninsured.

The CDC also has a guide for women looking for low-cost mammograms and Pap smears. The American Cancer Society at 1-800-ACS-2345 can direct you to services that provide free or cheap screenings for various types of cancer.

Keep an eye out, too, for any health fairs sponsored by local employers or community organizations. Free and low-cost screenings for common ailments, from depression to high cholesterol, are a routine part of these festivals.

Birth control and reproductive care: Many of the free and low-cost clinics provide reproductive care, or you can contact Planned Parenthood Federation of America, which specializes in free and low-cost help for men and women.

Prescriptions: Some companies market drug discount cards that might entitle you to small breaks on prescription prices, but if you're low-income, you might qualify for assistance programs run by the pharmaceutical companies. Two sites to check: NeedyMeds and the Partnership for Prescription Assistance.

Also, ask your doctor for free samples of any drugs prescribed. Most physicians have closets full of them.

Vision: Lions Club International is famous for its charity eye-care campaigns, which provide free screenings and recycled glasses. If you have a low-wage job but no vision coverage, the American Optometric Association may be able to hook you up with a volunteer doctor of optometry for a free exam. If you're 65 or older, the American Academy of Ophthalmology may be able to provide exams and treatment through its EyeCare America foundation at 1-800-222-EYES.

Dental: If going to the dentist terrifies you, the idea of going to a rookie dentist probably isn't going to put you any more at ease. But dental schools provide inexpensive and well-supervised treatment. To find the one nearest you, visit the National Institute of Dental and Craniofacial Research.

Some of the free clinics also provide dental services.

Emergency care: If you're facing a life-threatening situation, hospital emergency rooms are required to evaluate and stabilize you before asking about your ability to pay. A very limited number of hospitals are required to provide such care for free if you're poor, but the vast majority can bill you (and may hound you aggressively with collection agencies).

That's why if your situation is anything less than critical, you may want to explore alternatives other than emergency-room treatment. Many uninsured Americans wind up in the ER with noncritical situations, simply because they don't know where else to go.

With the information here, you now know some of your other options. Finally, three other things to consider:

* Medical coverage through your auto insurance. When you have a good health plan, you typically don't need the medical protection offered on your auto insurance policy. If you're uninsured, though, this coverage could pay your bills if you or your passengers are injured in an auto accident.

* Negotiating cash discounts. Some readers have reported being able to win discounts from hospitals and doctors when they agree to pay cash, while others say they've met resistance. One reader thought he'd be granted a 40% cash discount for his wife's labor and delivery, only to have the hospital renege on the deal and turn the unpaid 40% over to a collection agency.

* Bankruptcy protection. If you're hit with catastrophic medical bills, consider consulting with a bankruptcy attorney sooner rather than later. Bankruptcy laws have recently been toughened, but people with incomes below the median for their states can still erase medical bills and most other unsecured debts.

Not Enough Money For The Basics?

Remember free government cheese? These days, we have free government cell phones.


You read that right. A group funded by phone companies' universal service fees helps low-income Americans get phone service. This sometimes includes a prepaid cell.

This is just one of many public and private organizations that can help you meet basic needs -- from groceries to lifesaving medications -- for free.

These are programs that, as a taxpayer, you've helped underwrite. Just about everyone knows about food stamps and federal housing vouchers. But not everyone knows about those free cell phones or programs that provide:

* Eye exams and glasses.
* Rent assistance.
* Birth control, Pap smears and mammograms.
* Free shoes.
* Business attire for job seekers, both female and male.

Where do you find this kind of help? Read on.

Hungry for help

The Supplemental Nutrition Assistance Program, commonly  known as food stamps, is serving more Americans than ever: One in nine of us were using the program in March. To learn about SNAP and other federal food programs, including Women, Infants and Children, or WIC, and school lunches, click here.

Incidentally, that infamous Reagan-era government cheese was part of the Commodity Supplemental Food Program. The current food list doesn't include dairy products.

Feeding America, formerly known as America's Second Harvest, maintains a state-by-state list of food banks and soup kitchens. If more than one is available and you're broke, visit them all; every dollar you don't spend on grub can help pay rent or utilities.

Additional strategies:

* A food bank may give "first pick" to clients who volunteer.
* Check for edibles on The Freecycle Network. I've seen garden produce, tree fruit, infant formula, canned goods, cereal and even pet food offered.
* Some social-service organizations provide coffee and/or donated pastries or bagels to clients while they wait. If times are really tight, there's your breakfast or lunch.


A place to lay your head

Waiting lists are long for the federal government's rental assistance program. Some cities aren't taking new applicants for Section 8 housing vouchers. Be prepared to wait.

If you're out of work and eviction is imminent, call United Way's 211 referral line or a nonprofit such as the Salvation Army and be specific, such as: "Starting the first of the month I have nowhere to live." Because so many others are in the same predicament, you may not be able to get immediate help.


Get a list of all regional shelters. Check whether any churches let homeless people spend the night. If you have a disease or chronic condition, ask allied agencies about special housing.

Note: Any cash assistance you receive probably won't cover more than a room in a boardinghouse or a down-at-the-heels motel. But that still beats sleeping in a culvert.


Additional strategies:

* Work it off. Ask your landlord for a rent reduction in exchange for landscape work, cleaning the building, etc. Use this experience to apply for a resident manager job somewhere else. For more tips on free flops, see "How you can live rent-free."

* Put the word out among friends, asking for just one night per couch. Sing for your supper while you're there -- baby-sit, clean the tub, change the litter box. If you're useful, you might get asked to stay longer.


Staying warm, staying connected

Candles are not a safe substitute for electric lights. Ask your local utility about special rates for low-income residents. Your state's public utility commission can give information on policies such as a moratorium on shut-offs during winter.

The Low Income Home Energy Assistance Plan provides utility funding. Social-service agencies and nonprofits such as the Society of St. Vincent de Paul may also offer help with water, electricity or furnace fuels. Women's Apparel Bargains

Your phone company likely offers a bare-bones plan for low-income customers. Some states offer additional assistance with phone funds.

That Lifeline Across America program provides either a free cell phone or monthly savings on a land line, depending on where you live. You may also be able to borrow up to $200 worth of installation fees, interest-free. To find out how to apply, click here.

The Internet is no longer a frill. It's terrifically useful to job seekers who can post résumés, scan want ads nationwide and network with other unemployed folks. Web sites such as Freecycle and Craigslist can help you score freebies ranging from baby clothes to gleaned fruit. E-mail keeps you connected with family and friends.


Books at Buy.com!


Cheap Internet services are out there, but be sure to read the fine print. Say so long to the bells and whistles, though, and get used to dial-up. (You'll live.) The public library may have public computers, but access is often limited; at my library you get 30 minutes a day.

Have a laptop computer? Seek out free Wi-Fi, also available at many public libraries. Coffee shops, casual restaurants and bars offer the service, but this is awkward if you can't afford to buy anything. Some places are kicking out Wi-Fi users who don't pay the freight. If you were a loyal customer before your finances went south, a friendly manager may give you a break.

Or seek out other hot spots with Web sites such as the Wi-Fi FreeSpot Directory. A few searches turned up free Internet access in a pedestrian mall in Montana, a coin laundry in New Jersey and a supermarket in Alaska. You might be able to surf for hours.


For the health of it

Public health and community health centers offer care on a sliding scale. That may mean "free" if you're in sad financial shape. Sometimes the medications are free, too. To find a community health center or public health clinic in your area, click here.

Your kids may be eligible for free health insurance, including dental care, through the Insure Kids Now initiative. Some service organizations sponsor health giveaways. For example, Rotary clubs underwrite weekly health clinics in some cities, and many Lions Club chapters pay for hearing aids, eye exams and glasses. Contact local chapters to find out what's available.

More than three-fifths of Planned Parenthood clients use the family planning center as their primary health care provider. This includes women who are past childbearing age but still need annual exams plus blood-pressure checks, cholesterol screenings and other tests. Care is on a sliding scale, which could mean free. You can usually get free condoms there, too. To find a clinic, click here.

Sight for Students provides eye exams and glasses for uninsured youngsters. The Vision USA program offers free exams to low-income people with no insurance. EyeCare America incorporates several free-care projects, including help for people with diabetes and glaucoma.

Most pharmaceutical companies offer patient assistance programs for low-income people. Organizations such as NeedyMeds, the Partnership for Prescription Assistance, the Chronic Disease Fund and the Bureau of Prescription Help can get you started.

The HealthWell Foundation helps with co-pays and insurance premiums for people with certain chronic or life-threatening illnesses. The Patient Access Network Foundation offers the underinsured co-pay assistance.

Additional strategies:

* Doctors often get free prescription samples. Ask if samples of your medication are available.

* Walgreens and CVS drugstores offer free flu shots, free basic health screenings and free treatment for minor ailments. Certain conditions apply; click here for more information.

* Your city or county health department may offer well-baby checkups, immunizations and other basic preventive care, including screenings for sexually transmitted diseases.

* The National Breast and Cervical Cancer Early Detection Program offers screenings that may be free.

As I noted in "Do you have a problem swallowing your pride"  these programs are set up to help those in need. If you're having trouble keeping yourself housed, fed and healthy, accept a little aid for the short term.

You can give back later -- but first you have to get through today.
In search of services
To learn about more than 1,000 federal programs -- everything from child care to tax prep -- go to GovBenefits.gov.

Then check the "community services" pages in the front of the phone book. You'll see local, state and federal agencies, plus programs run by nonprofits such as the American Red Cross, Catholic Charities and the Salvation Army.Your city may also have a 211 phone number, a clearinghouse whose employees can direct you toward many types of assistance. About 80% of the country has 211 service,

Last year there was a "marked increase" nationwide in the number of calls for basic necessities

* In 2007, there were 1,942,193 calls for help with housing and/or utilities. In 2008, the number was 3,163,744.
* In 2007, there were 1,252,050 calls for help with food. In 2008: 1,716,650.

If there's no 211 service in your community, or even if there is, keep looking. Do an online search for social services both regional and national. You'll likely find that some programs are swamped. Yet even if an organization can't help it may refer you to others. Ask and keep asking.

Food banks often become de facto social-service clearinghouses. Francis Aviani of the St. Anthony Foundation in San Francisco says these pantries "have a very good (grasp) of other agencies in the community."

The St. Anthony Foundation offers numerous resources: hot meals, medical care, social workers, a food bank, clothing giveaways, Internet access and drug/alcohol rehab. You may be lucky enough to have a place like this near you. If not, you may need to contact more than one agency.

Additional strategies:

* Ask what documents are required, so you don't have to make a second trip.

* Don't just ask, "What time do you open?" Find out what time people start lining up, whether there's a sign-up sheet, how many days a week a program is offered, etc.

* Talk to other people waiting in line. They may know of other agencies that can help you.

* Religious organizations often provide help -- some with proselytizing, some without.

Mr. Dangerfield is an I.A.P.D.A Certified Debt Specialist whom has worked in the finance industry for 11 years. He manages www.beingbrokesuckstoday.com and is the author of "A Dangerfield Manifesto" and co-founder of SMG Holdings, the parent company of Squad Music Group, Dangerfield Artistic Entertainment SMG Publishing and Taboo Dangerfield Publishing
Follow me on twitter

Do you have trouble swallowing your pride?

The time to swallow your pride is not the day the electricity gets cut off.


Most Americans have never cashed an unemployment check, used a food bank, visited a public health clinic or even clipped coupons with zeal. We like to think that we can take care of ourselves, that we're the kind of people who offer help rather than take it.


That's a swell attitude to have -- until you're looking at a hungry child or an eviction notice. Don't let this happen. Public and private agencies will help you eat, pay the rent, keep the utilities on and get your kids immunized.

Pride shouldn't get in the way of survival. State and federal programs operate with the taxes you've been paying all these years, and private programs exist specifically to help those in temporary need.

Here's what you can expect as you test the public safety net. And remember: When times are better, you can give back.

You are far from alone

In this economy, more and more folks who once made a good living are joining the ranks of the unemployed or the working poor.

"We're (hearing) a lot of 'I never thought I'd be here,'" said Moses Carey Jr., the chairman of the Employment Security Commission of North Carolina.


If layoff is looming -- and even if one isn't -- you need to know your options. Some people don't even know how to start the unemployment process. (Not sure, either? Start here.)

Get over the idea that unemployment benefits are some kind of welfare. Unemployment insurance is just that: insurance against joblessness. Should your employer challenge the claim, you can appeal -- if you act quickly.


And now for a hard truth: Your old job might be gone forever, and your skill set might be obsolete. That's the case in North Carolina, where workers feel abandoned by the manufacturing, biotech and financial companies that once provided a good living, Carey said.

"What we tell them is they need to reinvent themselves so they can compete," he said.

Having gone back to school after three decades away, I can definitely say that yes, this is intimidating. But so is life without employable skills. Go in and talk to job counselors about vocational rehab, job retraining or higher education. Just be wary of incurring too much student debt.

Gimme shelter

How long could you keep a roof over your head if you lost your job? Would a month's worth of unemployment checks cover a month's worth of housing? Or suppose your rent goes up just as your hours get cut at work -- what then?

Think about this now. Right now. Maybe you could seek out cheaper digs or move in with a family member. Maybe you could take in a housemate or two. You could start searching for a job that will let you live rent-free, such as live-in nanny or apartment house manager.

Federally subsidized housing is available, but waiting lists are long, and in some cities the waiting lists are closed to new applicants. Sign up if you like, but don't count on getting a place anytime soon. Some states have rental assistance programs; click here to find out more.

Private organizations might be able to help. Requests for rent and utility assistance are up 40% at North Helpline, an emergency-services agency in Seattle. "We're hearing from people who have never needed this kind of service before," Executive Director Amy Besunder said.

Many clients volunteer at the agency because it makes them feel better about accepting assistance, Besunder said. So when you seek aid, ask if volunteers are needed. Note: A sustained record of service can bolster your résumé.


Get your resume on 75 job sites


House and apartment sharing are increasingly common in Portland, Ore., according to John Elizalde of the Northeast Emergency Food Program. Regular visits to food banks and soup kitchens are a survival tactic, he noted, because they let you divert grocery dollars toward rent or mortgage payments.

As a last resort, you can always flop on the couches of friends or family. But that's scarily close to homelessness. Don't rely on this as a tactic.

Having trouble with utilities? Call customer service, explain the situation and ask to set up a repayment plan. Some social service agencies, such as North Helpline, offer utility assistance; ask, ask, ask. You can also apply for the federal Low-Income Home Energy Assistance Program. An increasing number of those seeking help are working-class families, spokesman Mark Wolfe said.

Do not underestimate the power of coupon clipping. Rent, mortgage and car payments are hard to tweak, but your grocery bill "has a lot of wiggle room," said Stephanie Nelson of CouponMom.com.

Print FREE Grocery Coupons at Home


A number of sites and blogs match coupons to weekly sales and promotions. This can make a serious dent in grocery bills. Nelson, the author of the upcoming "The Coupon Mom's Guide to Cutting Your Grocery Bills in Half," says she spends as little as $3 for a spaghetti dinner for her family of five.


Coupons are available free on a ton of Internet sites. Save money on your favorite brands at Coupons.com. Click for many grocery coupons for free. You can even get them from a rewards program such as MyPoints, then use the points to get free gift cards for gasoline or groceries.

Are you worried about being embarrassed by the sighs and eye rolls from cashiers or other shoppers who might have to wait an additional second or two for a coupon to be scanned? A recent survey from Supermarket News indicates that 57% of respondents who used to feel embarrassed no longer care, as long as they are saving money.

They got over it. You can, too.

One in eight Americans is "food insecure," or lacking access to enough food, according to Feeding America, formerly known as America's Second Harvest. A day or two of lean eats until payday is one thing. A chronic lack of basic nutrition means that people should set aside notions of who, exactly, uses food banks.

When my mother used one when I was a child, I felt that she had compulsive need to explain herself. She used to take care of my sick brother. Now she has a good job. She is the first to contribute to food banks. Employees at Portland's food program hear that sort of thing a lot, Elizalde said.

"People just have to accept (their current situations)," he said. "At the end of the day, it's better to feed your kids and yourself."

To find food banks in your area, click here. Find out the details -- when they're open, what kind of documentation to bring -- before the cupboard is bare. Don't risk going home empty-handed.

If you're allowed to go more than once a week, do it. Or find out whether there is more than one food pantry you can use. These tactics will let you build a small pantry and set aside a few more dollars for rent or emergencies.

Sometimes the food bank isn't enough. You might get bread and noodles but little else. When demand is high and donations sparse, you may get nothing at all. If you're underemployed or unemployed, consider applying for the Supplemental Nutrition Assistance Program (the new name for the federal food stamp program) or the Women, Infants and Children nutrition program.

Again, don't wait until you're in crisis to check out these programs. It will take days or weeks to get approved.

Incidentally, getting food assistance is less embarrassing these days because paper coupons have been replaced by "electronic benefit transfer" cards. As far as the people in line behind you know, you're using a debit card.

Guarding your health

Whether you've lost your job or simply can't hack the insurance premiums any longer, start lining up health care before you actually need it. You can't work or look for work when you're sick.

Those who had insurance before being laid off can continue coverage under COBRA. Private health insurance might be cheaper, however. If you can't afford either one, I will be covering that in the near future.

Public health and community health centers can be literal lifesavers to those without coverage. Dr. Lauren Cianciaruso of the Loudoun County (Va.) Community Health Center has been seeing unemployed or uninsured patients whose chronic diseases were not being treated.

"We are able to get them the care they need," including medications, said Cianciaruso, chief medical officer.

Community health centers operate on a sliding-scale basis. So do county and state public health departments. A relative of mine who's on disability has gotten excellent, compassionate care at a public health clinic.

Yes, at times you may share the waiting room with drug addicts, the homeless or the mentally ill. Welcome to the real world, where you get to mingle with people who don't look like you. And, yes, asking for cheap or free doctor visits can be embarrassing. Do it anyway. Ignoring a health problem is never smart.

"You don't want to wait until you're so sick that you'll have to go to the emergency room. That's 10 times as expensive," said Dr. Charissa Fotinos of the Seattle area's public health department.

Besides, anyone who has paid taxes helped pay for these clinics. Once you're working, you'll be paying again. To find a community health center or public health clinic in your region, click here.

Lose the attitude

A common denominator of all these aid programs: questions. You will probably have to answer a lot of questions, and some will feel intrusive, such as marital status or personal assets. This can make newcomers develop a bit of "attitude," according to the Rev. June Cooper of the City Mission Society of Boston.

"They've never had to be under that kind of scrutiny," Cooper said.

Remember that everyone else has to answer the same questions. Remember, too, that this is where you are now. You won't be here forever.

When, exactly, will you be somewhere else? A job could surface next week, a cheaper apartment next month. Or maybe not. Stop obsessing over timetables, advised social worker Misha Tawakoli of Leesburg, Va.

"Don't look at the distant future. Look at immediate needs," she said. "You will get through this one day at a time."

The workings of the economy are beyond your control. Choosing to survive is an act of self-determination. Few people want to ask for help. But sometimes it just makes sense.

Save money today


Buy Authentic Mexican Food at MexGrocer.com!


Freeze: Ice cube trays aren't just for water. Find out more at "Frugality cubed -- creative ways with ice cube trays."

Pickup artist: The spare-change jar is a time-honored frugal hack. Fill it up faster with ideas from "Best places to find coins."

Mr.Dangerfield is an I.A.P.D.A Certified Debt Specialist whom has worked in the finance industry for 11 years. He manages www.beingbrokesuckstoday.com and is the author of "A Dangerfield Manifesto" and co-founder of SMG Holdings, the parent company of Squad Music Group, Dangerfield Artistic Entertainment SMG Publishing and Taboo Dangerfield Publishing
Follow me on twitter
From MSN Money

Thursday, October 1, 2009

Do you understand credit scoring?

How do credit scores work?


As a refresher for you and my readers to help improve your FICO credit score, below are the five factors that go into its calculation:

1. Paying on time: This represents 35 percent of your score. Payment history is the biggest factor for determining your score. This category includes the number and severity of any late payments. Payments of 120 days or more are the worst. The more credit problems you have, the lower the score.

2. Amount and type of debt: These make up 30 percent. This includes the total amount you owe, the amount you owe by account type such as revolving, installment or mortgage, the number of accounts on which you're carrying a balance and how much of the credit lines you have drawn down. Using your entire credit limit on a card lowers your score. Having credit cards with no balances ups your score. Free FICO® Credit Score Estimator

3. The length of time you've been using credit: This encompasses 15 percent of your score. This one you can't do much about today. But "paid as agreed" accounts that have been open for at least two years will help to increase your score.


4. The variety of accounts: This element represents 10 percent. A mix of credit accounts is good, but riskier types of credit will mean lower scores. For example, if most of your debt is in the form of finance-company loans, your score will be lower than if your debt is from student loans and mortgage loans, all other things being equal.


5. The number and types of accounts you've opened recently, generally in the last six months or so: These generate 10 percent of your score. Opening new accounts raises the question, "Can you afford a greater debt load, and also why have you opened them?" So, initially your score will go down. Once you show you can handle the new credit, the new credit will help your score. Credit Crisis Concerns? Get 20% off FICO credit scores now

To learn more about your credit score, better understand the factors affecting your score and what you can do about them, I suggest you go her Fico Scores/Reports. Fair Isaac Corp., the FICO score firm, has recently redone its Web site and has some excellent new educational features that you may find helpful. Finally, I want you to go to AnnualCreditReport.com to get a free copy of your credit reports and make sure there are no errors on them that are hurting your score. Around 20 percent of reports have some errors and yours may be one!
Finally, you will need to balance your desire to have a home now with the home and mortgage that you can afford with your current credit score. In today's tight credit environment, it will be super-hard and super-expensive to get a mortgage with your current credit. My advice is to work on rebuilding your score and wait until it improves before shopping for a home.

Can You Keep Your Kids Insured?


As Washington wrestles with health-care reform, states have been busy passing their own laws to allow many young adults to remain longer on a parent's health insurance.
In June, New York's governor signed one of the most recent measures -- a law allowing families to keep children up to age 29 on their employer-provided insurance, even if they aren't students. The adult child must not be eligible for other coverage, and he or she must work or reside in the state.
The Criteria
More than 20 states have similar laws. In most cases, the legislation extends coverage for young adults until their mid-20s, regardless of whether they are still in school. They typically require that the person not be married and not be eligible for other insurance. Parents usually have to pay more for the coverage, though that varies by state and plan.
"This is one way to decrease the underinsured liability for the state," says Edward Kaplan, a national health-care practice leader at Segal Co., a benefits consulting firm. Low Prices and Huge Discounts on Video Game Accessories. Shop GameShark Store.

Florida, New Mexico and Washington are among those that have extended coverage to nonstudents up to age 25. In Florida, insurers that offer dependent coverage must cover dependent children until they are 25. They also must offer policyholders the option to extend coverage until the children are 30.
Illinois passed a law last year that extends coverage to unmarried dependents until they're 26 regardless of their student status, and up to age 30 if they're veterans and have been honorably discharged.
Parents should check with their state insurance commission or their employers' human-resources departments to see if their adult children are eligible.


Extending parental coverage is often a better option than getting an individual policy for a young adult. "Dependent coverage tends to be a little richer than individual coverage," says Joel Cantor, a professor and director at the Center for State Health Policy at Rutgers University. It also typically is less expensive than an individual policy. That's especially true if the person has a pre-existing medical problem, which could make it difficult to find other coverage.


This Week’s Free Shipping and Special Offers

No Job, No Coverage
Research released in August by the Commonwealth Fund, a health-care research foundation, found that young adults age 19 to 29 are one of the largest segments of uninsured in the U.S. Almost 30% of people in that age group are uninsured because they don't think they need coverage, are no longer eligible for a parent's plan or work in entry-level or low-paying jobs that don't offer insurance.

Sara R. Collins, vice president for the Affordable Health Insurance Program at the Commonwealth Fund, says the problem likely will worsen because of the tight job market.

Lale Iskarpatyoti, a group and health-care practice leader at consulting firm Watson Wyatt, says most young adults "think nothing will happen to them so they look at the cost [of insurance] and don't get it."

But she knows the coverage is crucial. Her son -- a recent college graduate -- has health insurance at his new job. But it hadn't kicked in yet when he collided with another athlete during an Ultimate Frisbee game. The medical bill for his broken nose would have been thousands of dollars if his parent's policy had lapsed.

From Wall Street Journal


Mr. Dangerfield is an I.A.P.D.A Certified Debt Specialist whom has worked in the finance industry for 11 years. He manages www.beingbrokesuckstoday.com and is the author of "A Dangerfield Manifesto" and co-founder of SMG Holdings, the parent company of Squad Music Group, Dangerfield Artistic Entertainment SMG Publishing and Taboo Dangerfield Publishing
Follow me on twitter

How to buy a foreclosed home

Looking for a free foreclosure bank list?


Buying a foreclosure home often is appealing to house hunters trying to stretch their dollars. But finding a good one can be a challenge.
"The vast majority of the banks don't want us to advertise [foreclosure homes] as 'bank-owned' because it comes with a negative connotation," says Ryan Melvin, co-owner of More Realty Group in Las Vegas.
That means there's no sign on the front lawn indicating that it's a bank-owned house. And a buyer probably won't find a property advertised as a foreclosure in marketing materials, says Mr. Melvin, who specializes in real-estate owned properties, or REOs, those that have been reclaimed by a bank, typically after an unsuccessful foreclosure auction. Buy and Sell Real Estate Without Paying a Broker!

Where to Find Them

So, if you're considering the purchase of a home that's owned by a bank, you'll need to do some homework. Real Estate Agents, List Bank Reo, Foreclosure, Short Sale, Bpo Click Here!

One option: Go straight to the bank. Banks' Web sites will list properties that the financial institution has reclaimed. To find a list, do a Web search for "REO" and the name of the lender. Contact information for the property's listing agents is usually provided for each entry.


For a fee, other sites will hunt down properties for you. RealtyTrac.com, which helps people find foreclosure and pre-foreclosure properties, charges $49.95 a month, after a free seven-day trial. The company also recently launched BankHomesDirect.com, which charges $19.95 per month and lets people search just for REOs.Foreclosure Secrets Guide Click Here!

Foreclosures.com charges $49.95 per month, after a free seven-day trial.

You also can enlist the help of an experienced real-estate agent. Someone who works regularly with REOs might be able to track down the properties more easily than a traditional agent. The National REO Brokers Association has a searchable database of brokers on its site, nrba.com. The REO Network, reonetwork.com, offers a free listing of real-estate agents specializing in REOs.Get Paid To Clean Out Foreclosed Homes For Mortgage Co.'s & Banks Click Here!

Get a Thorough Inspection

When shopping around for a foreclosure property, it's important to know just how much work you're in for -- and how much it's going to cost you. Foreclosure homes are in various states of disrepair; some fixes are cosmetic, while others can be extensive.

Sometimes, people set their sights on bank-owned properties "like the word 'foreclosure' equals 'good deal,' " says Mark Goldman, a mortgage broker with Cobalt Financial and a real-estate lecturer at San Diego State University. But that's not always true.

Lenders aren't held to the same disclosure requirements as sellers who have lived in the home, mainly because the lender hasn't occupied the home to notice leaks or other problems. So an inspection is crucial.

"If there are lessons out of the last couple of years, it's certainly buyer beware," says Dan Steward, president of home-inspection firm Pillar to Post, which has a U.S. headquarters in Tampa, Fla.

"We have all heard the stories of people ripping the copper pipe and wiring out. People have literally gone to the light switch, disconnected the wire from the switch box and have pulled the wire through the drywall," Mr. Steward says. Some have ripped out toilets and kicked in walls or left faucets running before vacating the house, often out of anger.

While you don't need an inspector to tell you that the toilet is missing, he or she can tell you if there is damage 20 feet down the water line because of the way the toilet was ripped out, Mr. Steward says.

Other issues could pop up due to the property being vacant. Large banks will often hire a service to cut the grass, shovel the snow and winterize a home. But when homes aren't occupied, it's harder to catch small problems before they become big ones.
Come Prepared

To increase your chances of getting your offer accepted and having a quick closing process, have all paperwork and requirements in order before making an offer, says Duane Andrews, chief executive of Clear Capital, which provides valuation products for the mortgage and lending industries.

That includes having any financing approved and writing a clean offer -- not asking for minor repairs, for example.

Most bank-owned properties are sold "as is," Mr. Melvin says, so if there is something you want fixed, it's best to just factor that into the price you're offering.

But don't expect to bargain the listing price way down. Banks typically price their properties at a 20% to 30% discount to begin with, he says. If the property has been on the market for a week or two, don't expect the bank to drop the price; if the listing is older, you might have some wiggle room.

Make sure to follow directions when submitting the offer. "Most listing agents will have instructions on how we want buyers' agents to submit the offer," Mr. Melvin says. Delays can occur when instructions aren't followed.

And don't be surprised if the bank asks you to get approval from its mortgage operation. You often don't have to take the loan from their company, he says, but they may want to get a closer look at your finances to make sure you're a solid buyer.
From Wall Street Journal

Mr. Dangerfield is an I.A.P.D.A Certified Debt Specialist whom has worked in the finance industry for 11 years. He manages www.beingbrokesuckstoday.com and is the author of "A Dangerfield Manifesto" and co-founder of SMG Holdings, the parent company of Squad Music Group, Dangerfield Artistic Entertainment SMG Publishing and Taboo Dangerfield Publishing
Follow me on twitter